

L’articolo è stato aggiunto alla lista dei desideri


LIBRO INGLESE
 E-mail
 Facebook
 LinkedIn
 Twitter
 WhatsApp
Quantitative Portfolio Optimization: Advanced Techniques and Applications
(0)
Cliccando su “Conferma” dichiari che il contenuto da te inserito è conforme alle Condizioni Generali d’Uso del Sito ed alle Linee Guida sui Contenuti Vietati. Puoi rileggere e modificare e successivamente confermare il tuo contenuto. Tra poche ore lo troverai online (in caso contrario verifica la conformità del contenuto alle policy del Sito).
Grazie per la tua recensione!
Tra poche ore la vedrai online (in caso contrario verifica la conformità del testo alle nostre linee guida). Dopo la pubblicazione per te +4 punti 
95,00 €

-5%
100,00 €
+950
punti
Venditore: IBS
Articolo acquistabile con Carta del Docente

Articolo acquistabile con Carta Cultura Giovani e Carta del Merito

Articolo acquistabile con Carta della Cultura

Paga con Klarna in 3 rate senza interessi per ordini superiori a 39 €

Dati e Statistiche
 Salvato in 0 liste dei desideri
Quantitative Portfolio Optimization: Advanced Techniques and Applications
Disponibile in 5 gg lavorativi
95,00 €
-5%
100,00 €
95,00 €
100,00 €
-5%
Disponibile in 5 gg lavorativi
Altre offerte vendute e spedite dai nostri venditori
Libri in Inglese
Quantitative Portfolio Optimization: Advanced Techniques and Applications
Altri venditori
Prezzo e spese di spedizione
LIBRO INGLESE
Disponibile in 5 gg lavorativi

Venduto e spedito da
IBS
Spedizione Gratis
-5%
100,00 €
95,00 €
Altri venditori
Prezzo e spese di spedizione
LIBRO INGLESE
Disponibile in 5 gg lavorativi
Venduto e spedito da
IBS
Spedizione Gratis
-5%
100,00 €
95,00 €
Altri venditori
Prezzo e spese di spedizione

Tutti i formati ed edizioni
Promo attive (0)
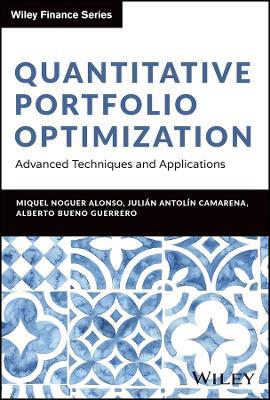
Expert guidance on implementing quantitative portfolio optimization techniques In Quantitative Portfolio Optimization: Theory and Practice, renowned financial practitioner Miquel Noguer, alongside physicists Alberto Bueno Guerrero and Julian Antolin Camarena, who possess excellent knowledge in finance, delve into advanced mathematical techniques for portfolio optimization. The book covers a range of topics including mean-variance optimization, the Black-Litterman Model, risk parity and hierarchical risk parity, factor investing, methods based on moments, and robust optimization as well as machine learning and reinforcement technique. These techniques enable readers to develop a systematic, objective, and repeatable approach to investment decision-making, particularly in complex financial markets. Readers will gain insights into the associated mathematical models, statistical analyses, and computational algorithms for each method, allowing them to put these techniques into practice and identify the best possible mix of assets to maximize returns while minimizing risk. Topics explored in this book include: Specific drivers of return across asset classes Personal risk tolerance and it#s impact on ideal asses allocation The importance of weekly and monthly variance in the returns of specific securities Serving as a blueprint for solving portfolio optimization problems, Quantitative Portfolio Optimization: Theory and Practice is an essential resource for finance practitioners and individual investors It helps them stay on the cutting edge of modern portfolio theory and achieve the best returns on investments for themselves, their clients, and their organizations.
Leggi di più
Leggi di meno
Editore:
Collana:
Wiley Finance
Anno:
2025
Rilegatura:
Hardback
Pagine:
384 p.
Testo in English
Dimensioni:
234 x 158 mm
Peso:
703 gr.
EAN:
9781394281312

L'articolo è stato aggiunto al carrello
Informazioni e Contatti sulla Sicurezza dei Prodotti
Le schede prodotto sono aggiornate in conformità al Regolamento UE 988/2023. Laddove ci fossero taluni dati non disponibili per ragioni indipendenti da IBS, vi informiamo che stiamo compiendo ogni ragionevole sforzo per inserirli. Vi invitiamo a controllare periodicamente il sito www.ibs.it per eventuali novità e aggiornamenti.
Per le vendite di prodotti da terze parti, ciascun venditore si assume la piena e diretta responsabilità per la commercializzazione del prodotto e per la sua conformità al Regolamento UE 988/2023, nonché alle normative nazionali ed europee vigenti.
Per informazioni sulla sicurezza dei prodotti, contattare productsafetyibs@feltrinelli.it
L’articolo è stato aggiunto alla lista dei desideri
